There is a story I think about often. A young couple — one child already, a second on the way. They were the kind of family that had done everything right. Good jobs, a home they owned, a budget they followed. Responsible people by every measure.
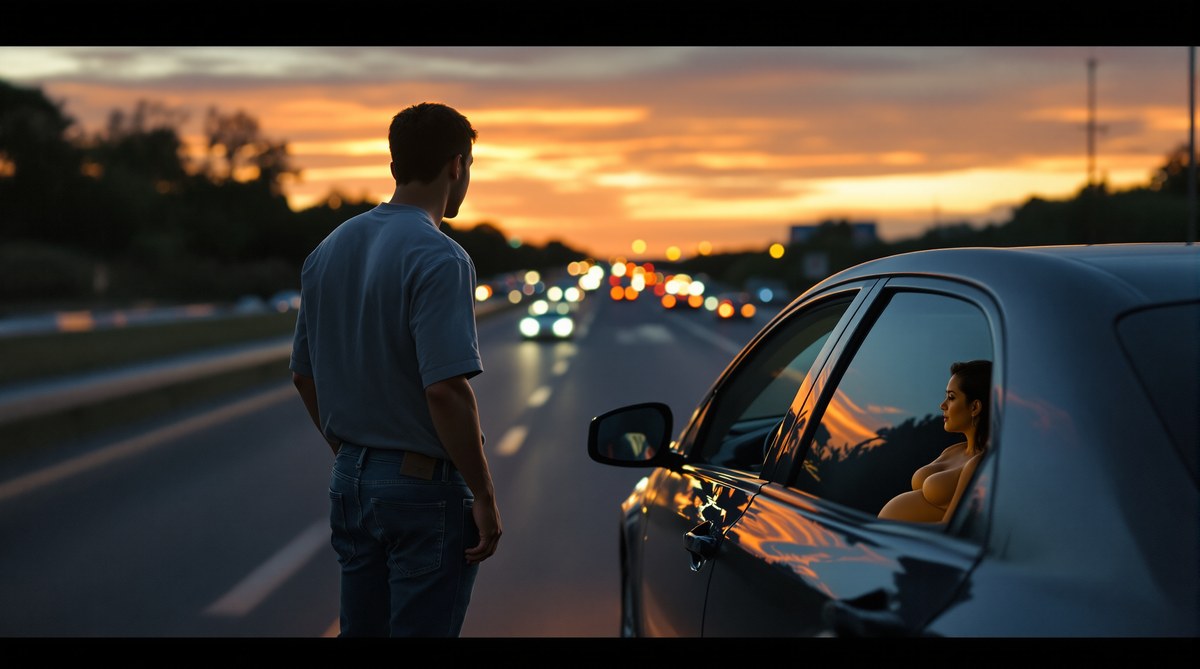
One afternoon, they pulled over on a highway to help someone who had broken down. The husband got out to see what had happened. He went back to his wife, who was sitting in the passenger seat, and told her to call for paramedics. Then he stepped back outside.
A speeding car never saw him.
He was killed on the spot. In the blink of an eye. No warning. No gradual illness. No time to plan.
The insurance agent who had helped this couple had done something unusual. When they came in for car insurance and homeowners coverage, the agent didn't just process the policies and move on. He sat with them. He looked at their full picture — the mortgage, the income, the baby already here and the one coming. He asked the question most agents skip:
"What happens to your family if something happens to you?"
They didn't have an answer. So he gave them one. He wrote a life insurance policy that day — not a large one, but enough. Enough for a proper funeral. Enough to pay off the mortgage so she wouldn't lose the home. Enough to let a pregnant widow stay home after the birth of her second child and raise her babies without being forced back to work in weeks.
The Misnomer That Costs Families Everything
Here's the thing most people don't know about life insurance: it is not like car insurance.
With car insurance, you can cancel your policy today and buy a new one tomorrow. You can switch carriers, change coverage, start and stop as your situation changes. The product waits for you. It has no opinion about your health, your age, or what you've been diagnosed with recently.
Life insurance doesn't work that way. And because it has the word "insurance" in its name, most people assume it operates the same way. That assumption is one of the most dangerous in personal finance.
To purchase life insurance, you must qualify for it — medically and financially. The insurer evaluates your age, your health history, your current conditions, your family medical history, and in many cases requires a medical exam. A diagnosis of diabetes, heart disease, cancer, or even certain mental health conditions can make you uninsurable — or push your premiums to a level that makes coverage unaffordable. You cannot simply decide to buy it when you need it. By then, it may no longer be available to you.
This is the misnomer that costs middle-class families everything. They think they'll get around to it. They think it'll be there when they're ready. They think "I'm still young, I'll deal with it later." And then later arrives in the form of a diagnosis, a condition, or — as in the story above — a moment with no warning at all.
The Moments That Make It Critical
Middle-class families have a particular vulnerability that often goes unacknowledged. They have too much to lose — real assets, real obligations, real people depending on one or two incomes — but they also operate close enough to the edge that losing one income would be catastrophic.
Three life events in particular create the window when life insurance is most needed — and when people are most likely to still be able to get it:
Starting a Career
A 25-year-old entering the workforce is typically at their peak insurability — young, healthy, no major diagnoses yet. A term life policy at this age can cost as little as $20–$30 a month for $500,000 in coverage. Ten years later, that same person may have a family, a mortgage, and a blood pressure issue that doubles their premium or disqualifies them entirely. The window is open now. Most 25-year-olds walk right past it.
Starting a Family
The moment a child arrives — or is on the way — the stakes change entirely. There is now a person whose entire world depends on you being present and financially functional. If the primary earner disappears, what happens to the family? How long can the remaining spouse cover the mortgage, the childcare, the groceries? Without life insurance, the answer is usually: not long.
Buying a Home
A mortgage is a 30-year commitment. If the person making that mortgage payment dies in year 3 or year 7 or year 15 — what happens to the home? In many cases, the answer is foreclosure. The family loses the person and then loses the home. Life insurance makes the mortgage disappear so the family can keep what they've built.
The Qualifying Process — What Most People Don't Know
When I explain to clients that life insurance works more like a mortgage than a car insurance policy, the room changes. Something clicks. They understand it differently.
When you apply for a mortgage, the bank doesn't just hand you money because you asked. They review your credit, your income, your debt-to-income ratio. They evaluate risk. And based on that evaluation, they either approve you, approve you with conditions, or decline you.
Life insurance underwriting works the same way. The insurance company evaluates your risk of dying during the policy term. And that evaluation is thorough:
- Age — The younger you are, the lower your risk, the lower your premium. Every year you wait costs you money.
- Current health — Weight, blood pressure, cholesterol, blood sugar. Many conditions that seem manageable today can trigger premium increases or coverage denial.
- Medical history — Past diagnoses, surgeries, hospitalizations. Items that were treated years ago can still affect your rating.
- Family medical history — If heart disease, cancer, or diabetes runs in your family, underwriters factor that in even if you personally have never been diagnosed.
- Lifestyle factors — Tobacco use, certain high-risk occupations or hobbies can affect premiums significantly.
- Prescription history — The medications you take tell underwriters about conditions you may not have fully disclosed.
The people who are best positioned to get excellent life insurance rates are also the people who feel least urgency to buy it — young, healthy, no diagnoses, everything going well. That is exactly when you should be buying it. Not because you think you're going to die. Because you want to lock in access to coverage while you still can.
"By the time most people decide they need life insurance, something has already happened that makes getting it harder or more expensive. The application doesn't care about your intentions. It cares about your health today."
What the Right Agent Does
The story of that young couple on the highway stays with me because of one specific detail: they didn't come to their agent asking for life insurance. They came for car insurance and homeowners coverage. The agent read their situation — young family, mortgage, baby on the way — and proactively asked the question that most agents skip because it's uncomfortable or because they're in a hurry to close the existing transaction.
That question — what happens to your family if something happens to you? — is the most important question in personal finance. It's also the one that gets skipped most often.
A good agent doesn't just sell you what you asked for. They look at your full picture. They identify the gaps. They have conversations that feel uncomfortable but that can be the difference between a family that survives a tragedy and a family that crumbles under one.
If you have a mortgage and no life insurance, you have a gap.
If you have children and no life insurance, you have a gap.
If your family depends on your income and no life insurance exists to replace it, you have a gap.
The time to close that gap is not when you need it. It's right now, while the door is still open.
— Patrick Villalobos, Owner · Lakeside Insurance Partners · NPN 12112672